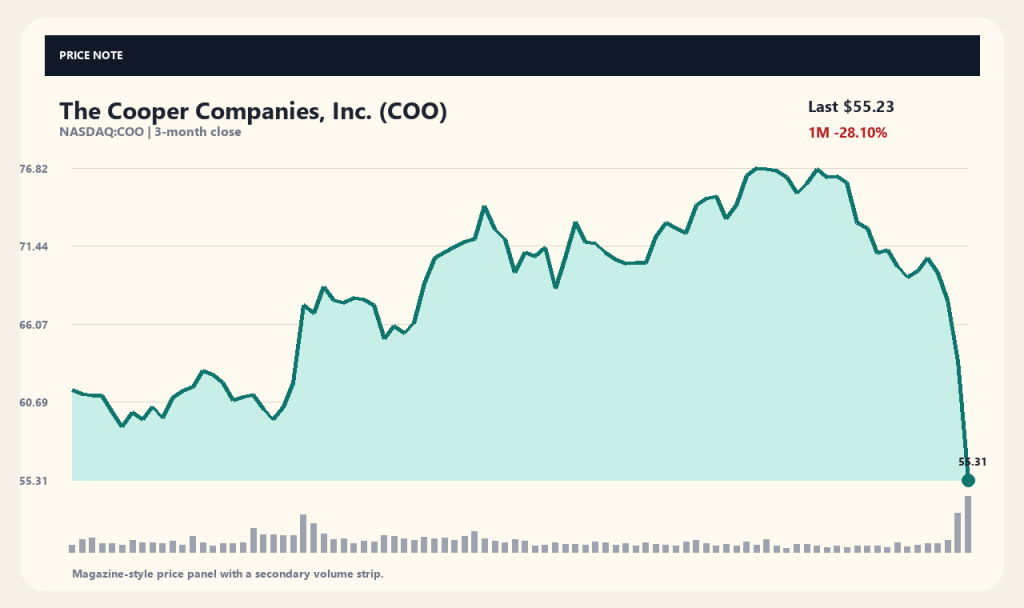
Global medical device maker The Cooper Companies (COO) saw its stock plunge 13.0% in a single day to close at $55.23. The sharp drop came alongside its Q3 fiscal 2026 earnings release, triggered by a combination of headwinds. Major financial media outlets reported that a lowered full-year guidance and the cancellation of its surgical unit sale disappointed the market.
Investors are closely tracking the company's financial results and the future direction of its core divisions. Fractures have emerged in its dual business structure, which consists of contact lens maker CooperVision and women's health/fertility product maker CooperSurgical. Investors need to evaluate whether management's restructuring strategy can effectively drive long-term growth beyond this short-term slump.
CooperSurgical Sale Cancellation Signals Business Uncertainty
Cooper Companies had been pursuing the sale of its CooperSurgical division but decided to withdraw after failing to receive an attractive valuation. Reports from Motley Fool and Bank of America cited heightened competition and deteriorating market conditions as the primary obstacles to obtaining an adequate price. This setback derails the company's plan to improve its balance sheet and focus on its primary business through the divestiture.
The failed subsidiary sale goes beyond a simple canceled deal, directly impacting how the market values the firm. With expected cash inflows and debt reduction plans now uncertain, market disappointment triggered heavy selling. As the cleanup of non-core assets gets delayed, the company faces the challenge of operating both divisions while proving it can improve profitability on its own.
Behind the Lowered Guidance and Revenue Slump
Alongside its Q3 2026 earnings release, the company lowered its forward financial guidance. Media reports from Investor's Business Daily and others noted that Q3 revenue fell short of Wall Street expectations, confirming a temporary pause in overall growth. The slowdown in revenue growth made reaching full-year targets increasingly difficult, driving the decision to cut guidance.
However, the earnings report was not entirely negative. According to Motley Fool, the company recorded a $307 million tax benefit in the quarter alongside record free cash flow that partially offset weaker revenue momentum. Operating cash flow reached $953 million, demonstrating that cash generation from core operations remains relatively robust.
Stock Metrics and Technical Indicators After the Sharp Sell-Off
Immediately following the earnings announcement, Cooper Companies stock dropped 13.0% from its previous close of $63.48 to $55.23. This extends a recent downturn, bringing its 1-week loss to 20.79% and its 1-month loss to 28.1%. Approaching its 52-week low of $51.01 against a 52-week high of $89.83, the stock's relative price position indicator dropped to 10.87%.
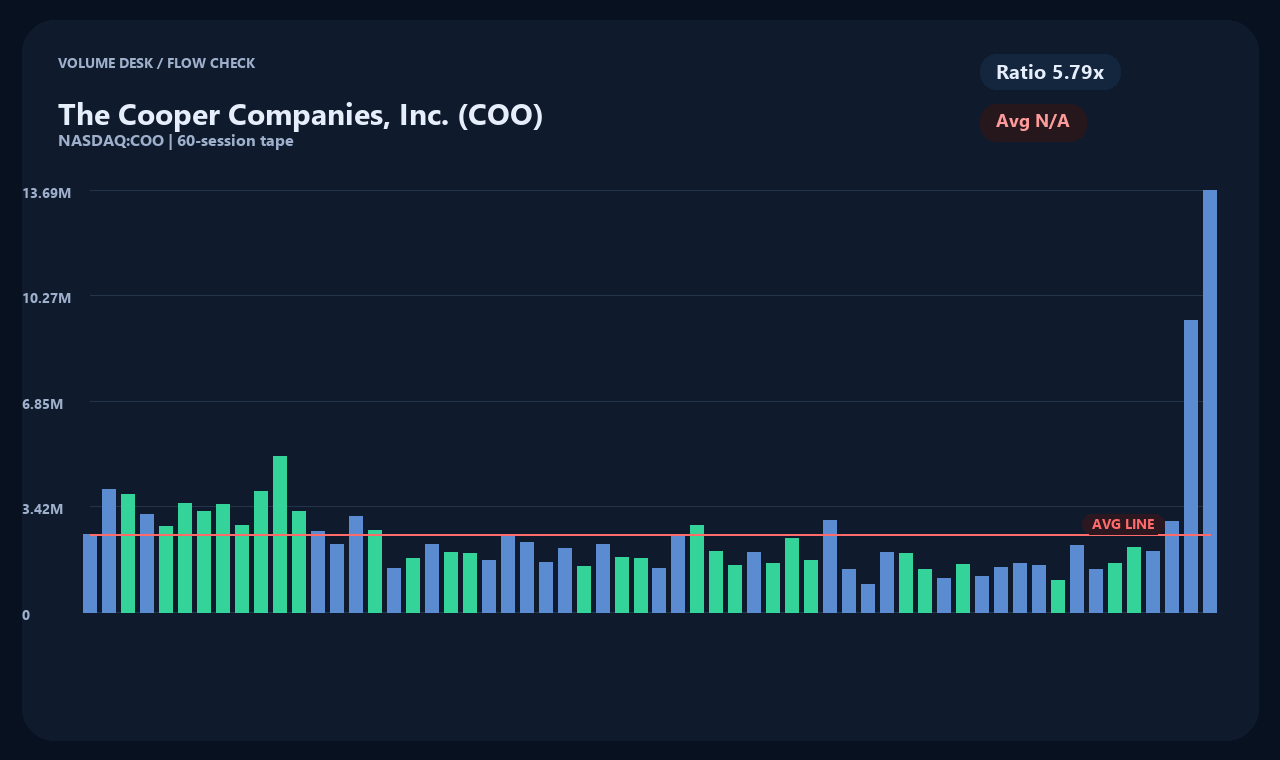
Trading volume surged to 13,591,656 shares on the day, roughly 5.79 times its average daily volume of 2,346,111 shares. A significant technical gap emerged as the stock fell more than 22% below both its 20-day moving average ($71.61) and 60-day moving average ($71.47). However, the surge in volume should not automatically be viewed as dip-buying or bullish accumulation, as it likely reflects a mix of stop-loss selling driven by shifting fundamentals.
Financial Health Analysis and Limits to Resuming a Sale
A look at Cooper Companies' financial statements shows total revenue of approximately $4.231 billion and net income of around $235.8 million. Total debt stands at approximately $2.7266 billion against cash holdings of $138.8 million, indicating a notable debt burden. Under these financial conditions, the failure to reduce debt through the CooperSurgical sale means the company must absorb interest expenses and balance sheet risks for the foreseeable future.
Available data does not confirm whether the CooperSurgical sale is permanently off the table or if it could be revived when market conditions improve. Changes in market interest rates or competitor movements could reopen M&A opportunities down the road. How management addresses debt management and subsidiary plans during the next earnings call or official presentation will be a key area to monitor.
Key Factors for Investors to Watch Going Forward
Future stock performance and valuation adjustments depend on a demand recovery for contact lenses in the core CooperVision unit. Sustaining market share and benefiting from global contact lens market growth will serve as the primary drivers to overcome the near-term revenue slump. Investors also need to verify whether upcoming Q4 results can meet these newly lowered expectations.
A stock reaching historically low levels following a rapid decline should not automatically be considered undervalued. Investors must first evaluate whether the company's $27 billion debt load and the opportunity costs of the delayed sale are offset by business performance. Signs of a fundamental rebound will only become clear once profitability in the surgical division improves and free cash flow durability is confirmed.
Data as of (2026-09-11T04:02:50): Price $55.23 USD · 1-Day -13.0% · 1-Week -20.79% · 1-Month -28.1% · 3-Month -18.41%
[Sources and Timestamps]
Market data: yahoo_chart_api · Timestamp: 2026-09-11T04:02:50. Related coverage sources: MT Newswires, Motley Fool, Investor's Business Daily. Article headlines serve as context; primary sources such as company press releases and official filings should be independently verified.
This article is provided for informational purposes only and does not constitute investment advice.
This content is for informational purposes only and is not investment advice.
 StockBrief
